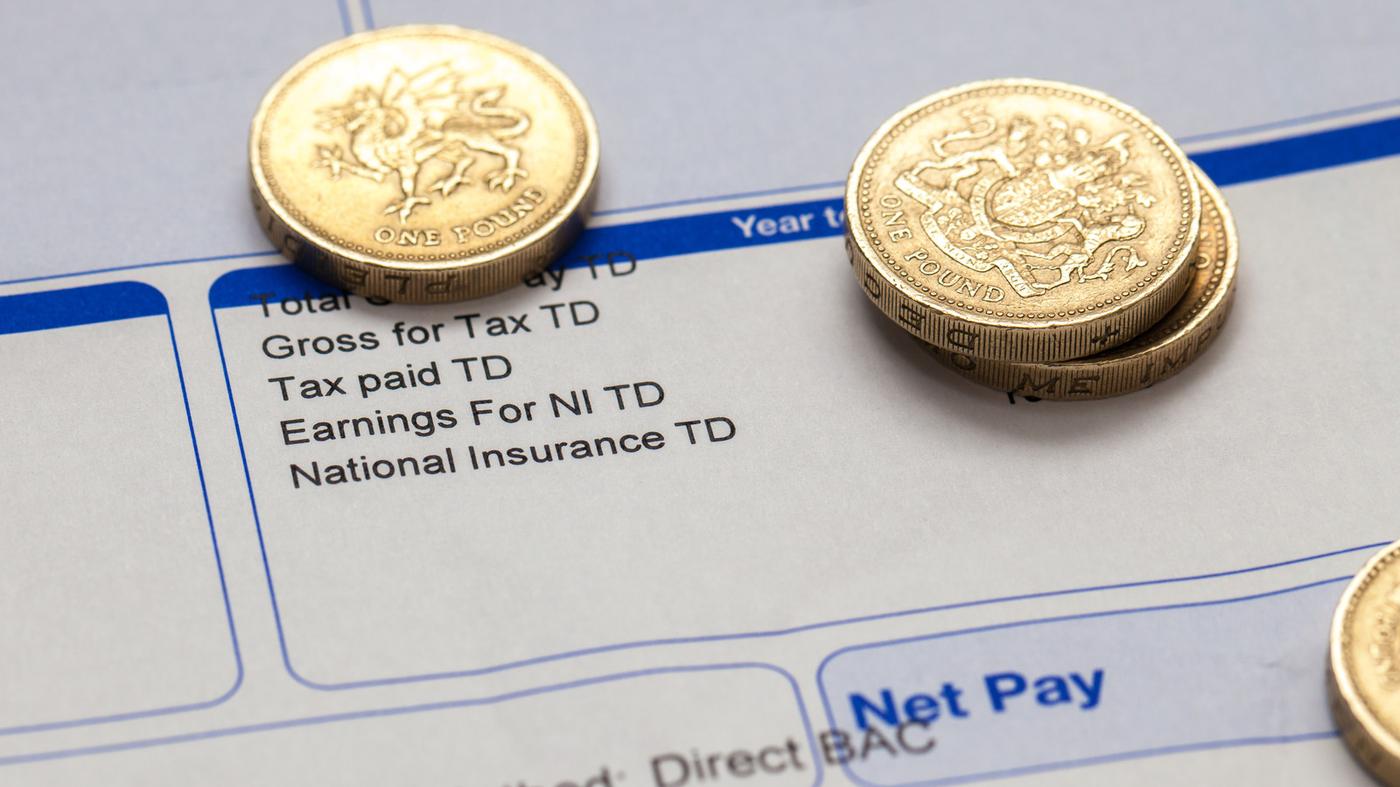
Pay slip up close
5 min read

Operating payroll

If you employ staff, you’ll normally need to operate payroll to calculate their pay and deductions, keep payroll records and report information to HMRC. This guide explains the main steps involved in setting up and running payroll.

What is payroll?

Payroll is the process you use to calculate and pay your employees and report information about their pay to HMRC.

As well as an employee’s normal salary or wages, payroll may need to take account of payments such as:

  • overtime, bonuses and commission
  • tips paid through payroll
  • expenses and benefits
  • holiday pay
  • statutory payments, such as Statutory Sick Pay and statutory payments relating to parental leave.

Payroll is also used to calculate deductions from employees’ pay, which can include Income Tax, employee National Insurance contributions, workplace pension contributions and student or postgraduate loan repayments.

PAYE (Pay As You Earn) is HMRC’s system for collecting Income Tax and National Insurance from employment. Employers use payroll to calculate the amounts due and report the required information to HMRC.

Do I need to register for PAYE?

Most businesses that employ staff need to register with HMRC as an employer and operate PAYE.

You normally need to register if any of your employees:

  • are paid at or above the relevant PAYE registration threshold
  • receive expenses or company benefits
  • have another job
  • receive a pension.

You may not need to register for PAYE if none of these circumstances applies, although you’ll still need to keep payroll records.

You must also register as an employer if you need to operate PAYE for other reasons, such as paying yourself as a director of a limited company. Different registration requirements can apply if you engage subcontractors under the Construction Industry Scheme (CIS).

If you need to register, you should generally do this before the first payday, but you cannot normally register more than two months before you start paying employees.

HMRC will provide an employer PAYE reference and Accounts Office reference, which you’ll need when operating payroll and making payments to HMRC.

What is Real Time Information (RTI)?

Real Time Information (RTI) is the system employers use to report payroll information to HMRC. Instead of reporting employees’ pay and deductions at the end of the tax year, you normally send information to HMRC each time you pay your employees.

Most payroll information is reported using a Full Payment Submission (FPS). You must normally send an FPS to HMRC on or before the day you pay your employees. It includes details of their pay and deductions, such as Income Tax and National Insurance contributions.

You may also need to send an Employer Payment Summary (EPS). For example, an EPS can be used to report certain adjustments that affect how much you need to pay HMRC, or to tell HMRC that you have not paid any employees in a tax month.

Your HMRC-recognised payroll software will normally create and send these reports electronically as part of running your payroll.

It’s important to submit accurate payroll information on time. Late or incorrect reports can result in penalties in some circumstances.

What information do I need when an employee starts?

Before you pay a new employee for the first time, you’ll need to collect information about them so that you can add them to your payroll and report the correct details to HMRC in your Full Payment Submission (FPS).

Ask the employee for their P45 from their previous employer, if they have one. If they don’t have a P45, you’ll normally need them to complete HMRC’s starter checklist. You should keep the checklist for your records rather than send it to HMRC.

Information Why you need it
Personal details You’ll need details such as the employee’s full name, address, date of birth and gender for payroll reporting.
National Insurance number Use the employee’s NI number if they have one. An employee can start work without one, provided they can prove their right to work in the UK.
Start date Record the date their employment started.
Tax information Use their P45 where available. If they don’t have one, use the information from HMRC’s starter checklist to help determine the correct starting tax code.
National Insurance category You’ll need the appropriate category letter to calculate employee and employer National Insurance correctly.
Student and postgraduate loans Establish whether deductions are required and which repayment plan applies. HMRC may also send you a notice instructing you to start or stop deductions.
Payroll information Record information such as how often the employee will be paid and the information needed to calculate their pay.
Normal working hours You’ll need to report the appropriate employee hours information required by HMRC through payroll.

You’ll also need information needed to pay the employee, such as their bank details, although not all of the information you collect when someone starts work is reported to HMRC.

How much do I pay my staff?

The amount an employee earns and the amount they actually receive will usually be different. Payroll calculates this using the formula:

Gross pay – deductions = net pay

Payroll on iPad

Gross pay

Gross pay is the total amount an employee earns before deductions. Depending on their employment terms, this could include:

Find out more

  • salary or wages
  • overtime
  • bonuses or commission
  • holiday pay
  • statutory payments, such as Statutory Sick Pay or payments relating to parental leave
  • other payments they’re entitled to.

You must make sure an employee’s pay complies with the National Minimum Wage or National Living Wage rules where these apply.

Close
pound coins

Minus Deductions

Deductions are amounts taken from gross pay before the employee is paid. These may include:

Find out more

  • Income Tax

  • employee National Insurance contributions

  • student or postgraduate loan repayments

  • employee workplace pension contributions

  • Payroll Giving donations
    other deductions you’re required or authorised to make.


Close
Payslip

Equals Net Pay

Net pay is the amount left after the relevant deductions have been made. 

Find out more

This is the amount you pay to the employee.

Close
payroll software for small business

Costs that aren't deductions

Some employment costs aren’t deducted from the employee’s gross pay.

Find out more

For example, employer National Insurance and employer workplace pension contributions are paid by the employer in addition to the employee’s pay.


Close
1:27

Video: How do I calculate payroll deductions?

by Informi

You can run payroll yourself or pay someone else to do it for you, such as an accountant, bookkeeper or payroll provider.

If you outsource your payroll, you’ll still need to provide accurate and timely information about your employees and their pay. As the employer, you remain responsible for meeting your PAYE responsibilities, even if someone else runs your payroll.

If you run payroll yourself, you’ll normally use payroll software to calculate:

  • gross pay
  • Income Tax
  • employee and employer National Insurance contributions
  • student and postgraduate loan repayments
  • workplace pension contributions
  • statutory payments and other relevant deductions
  • net pay.

Your software should also enable you to report the required payroll information to HMRC through Real Time Information (RTI). You’ll normally do this by sending a Full Payment Submission (FPS) on or before the employee’s payday.

HMRC provides Basic PAYE Tools, which may be suitable for employers with fewer than 10 employees. Alternatively, you can use commercial payroll software. Payroll software will normally make the calculations for you, but HMRC provides tools and tables that you can use to check payroll calculations manually.

Watch the video below for an introduction to how PAYE works, including how an employee’s tax code affects the Income Tax deducted from their pay.

What payroll documents do I need to give my employees?

As an employer, you’ll need to provide employees with certain payroll documents at different stages of their employment.

  • Documentation in filer
    Payslips

    You must give employees and workers a payslip on or before their payday. It must show their gross pay, deductions and net pay. Where pay varies according to the amount of time worked, the payslip must also show the relevant number of hours worked.

  • Working on iMac
    P45

    When an employee leaves, you must give them a P45 showing information including their leaving date, pay and tax in the tax year to date and tax code. Your payroll software will normally produce this.

  • Using calculator
    P60

    You must give a P60 to employees who are still working for you on 5 April. It summarises their pay and tax for the tax year and must be provided by 31 May, either on paper or electronically.

  • Looking at computer
    Reporting of benefits and expenses

    If you provide taxable benefits or expenses, you may need to report them to HMRC. Depending on how they’re reported, this may involve a P11D or reporting the benefit through payroll. Where a P11D is required, you must also provide the employee with details of the information reported.
Checklist: What payroll records do I need to keep?

You’re responsible for keeping accurate payroll records, even if an accountant, bookkeeper or payroll provider runs payroll on your behalf.

You must generally keep PAYE records for three years from the end of the tax year they relate to. HMRC can check your records to make sure you’ve reported and paid the correct amounts. If you don’t keep adequate records, HMRC may estimate what you owe and charge a penalty.

Other employment records may have different retention requirements. For example, separate rules apply to records used to demonstrate compliance with the National Minimum Wage and records relating to statutory leave and holiday pay.

In general, your payroll records should include:

You must be logged in to use this checklist

Login or Register

End of Article
Share this content

Brought to you by:

AAT Business Finance Basics

AAT Business Finance Basics are a series of online e-learning courses covering the core financial skills every business needs. They draw from AAT’s world-leading qualifications and will quickly build your knowledge on key topics including bookkeeping, budgeting and cash flow.

Visit partner's website

Register with Informi today:

  • Join over 30,000 like-minded business professionals.
  • Create your own personalised account with curated reading lists and checklists.
  • Access exclusive resources including business plans, templates, and tax calculators.
  • Receive the latest business advice and insights from Informi.
  • Join in the discussion through the comments section.

or